

研究团队
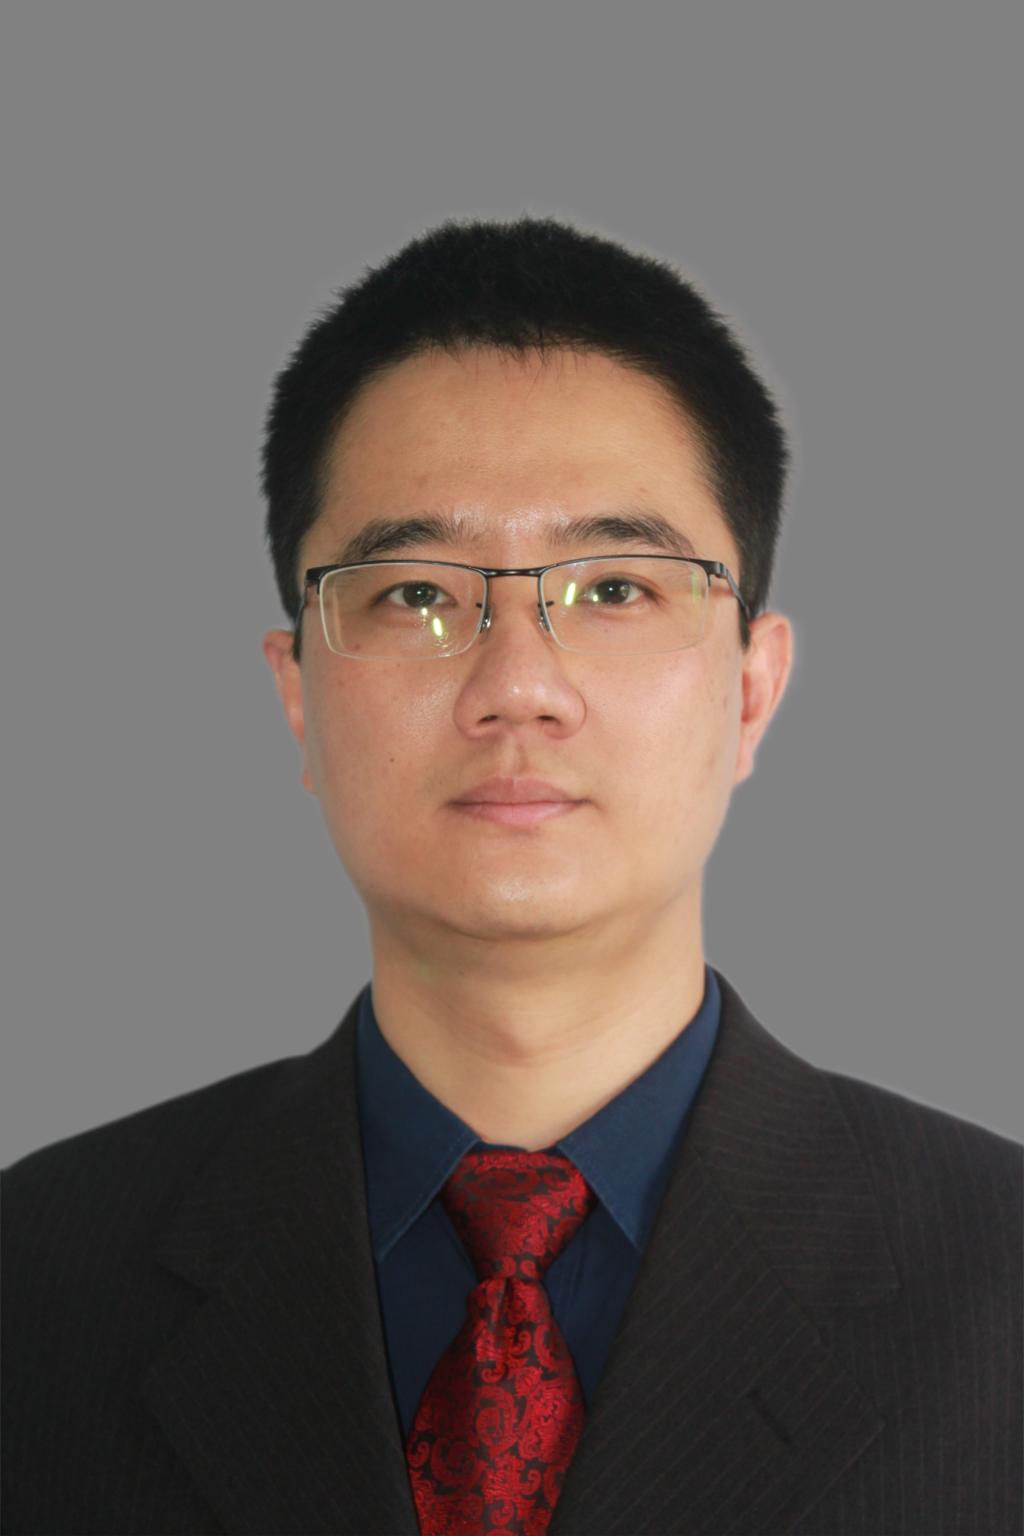
个人简介
中国人民大学财政金融学院,教授、博士生导师,应用金融系主任,未来金融创新工程中心副主任
教育背景
2010年8月—2015年5月,埃默里大学(Emory University),经济学博士
2006年8月—2008年9月,印第安纳大学(Indiana University, Indianapolis),经济学硕士
2002年9月—2006年7月,对外经济贸易大学,经济学、文学双学士
代表作品
论文
[1] Forecasting Market Return using Anomalies: Evidence from China, with Jianqiu Wang and Zhuo Wang, International Journal of Forecasting, 2025, 41, 1278-1295
[2] Dynamic Market Timing in Mutual Funds, with Jeffrey Busse, Jing Ding, and Lei Jiang, Management Science, 2024, 70, 3470-3492
[3] Identifying Factors via Automatic Debiased Machine Learning, with Esfandiar Maasoumi, Jianqiu Wang, and Zhuo Wang, Journal of Applied Econometrics, 2024, 39, 438-461 (Recognized by Wiley as a Top 10 most-cited article in the Journal of Applied Econometrics in 2024)
[4] Asymmetry and the Cross-section of Option Returns, with Jianqiu Wang, Sijie Yang, and Dexin Zhou, Journal of Financial Markets, 2024, 71, 100932
[5] The Value of FinTech Innovations: Evidence from China, with Zhigang Qiu, Jianqiu Wang, and Sijie Yang, Economic and Political Studies, 2024, 12, 1-19
[6] On the conditional performance of the IVOL anomaly, with Jianqiu Wang and Jiening Pan, International Review of Economics and Finance, 2024, 89, 337-350
[7] Disagreement, Speculation, and Idiosyncratic Volatility Puzzle with Jianqiu Wang, Jiening Pan, and Ying Jiang, Journal of Empirical Finance, 2023, 72, 232-250
[8] The Role of Anchoring on Investors’ Gambling Preference: Evidence from China, with Zhuo Wang and Ziyue Wang, Pacific-Basin Finance Journal, 2023, 80, 102054
[9] Nonlinearity in the Cross-Section of Stock Returns: Evidence from China, with Jianqiu Wang, Guoshi Tong, and Dongxu Chen, International Review of Economics and Finance, 2023, 85, 174-205
[10] Stock Return Asymmetry in China, with Dongxu Chen and Yifeng Zhu, Pacific-Basin Finance Journal, 2022, 73, 101757
[11] Stock Return Asymmetry: Beyond Skewness, with Lei Jiang, Guofu Zhou, and Yifeng Zhu, Journal of Financial and Quantitative Analysis, 2020, 55, 357-386 (Lead article)
[12] Asymmetry in Stock Returns: An Entropy Approach, with Lei Jiang, and Guofu Zhou, Journal of Financial and Quantitative Analysis, 2018, 53(4), 1479-1507
[13] A Test of Asymmetric Dependence, with Lei Jiang, Esfandiar Maasoumi, and Jiening Pan, Journal of Applied Econometrics, 2018, 33, 1026-1043
[14] Testing the Long-run Risk Model: A Kalman Filter Approach, with Jianqiu Wang, Annals of Financial Economics, 2018, 13(4)
[15] The Gap between the Conditional Wage Distributions of Incumbents and the Newly Hired employees: Decomposition and Uniform Ordering, with Esfandiar Maasoumi, and M. Melinda Pitts, Advances in Econometrics, 2014, 33: 587-612
著作
《金融大数据分析》(高等学校新文科教材金融科技系列),与周德馨合著,中国人民大学出版社,2025
《资产定价与机器学习》(高等学校新文科教材金融科技系列),独著,中国人民大学出版社,2023
科研项目
[1] 国家自然科学基金面上项目,基于生成式人工智能的公司网络与资产定价:理论、测度与应用,项目负责人,2026—2029
[2] 国家自然科学基金面上项目,投资组合优化和定价因子选择:基于非线性预测和机器学习的视角,项目负责人,2022—2025
[3] 国家自然科学基金青年基金项目,资产收益率的广义不对称相关性:基于信息熵的统计检验和对股票定价影响的实证研究,项目负责人,2019—2021,项目绩效评估为“优”
[4] 国家自然科学基金重大项目,数字经济的博弈论基础,主要参与人,2022—2026
[5] 科学技术部国家重点研发计划,金融数据合成与智能模型风险监测关键技术及应用,主要参与人,2024—2026
[6] 中国人民大学科研基金面上项目,基于非线性机器学习方法的中国股票市场定价变量选择及因子定价模型研究,项目负责人,2020—2022
[7] 中国人民大学新教师启动基金项目,对股票收益不对称相关性的假设检验,项目负责人,2016—2018